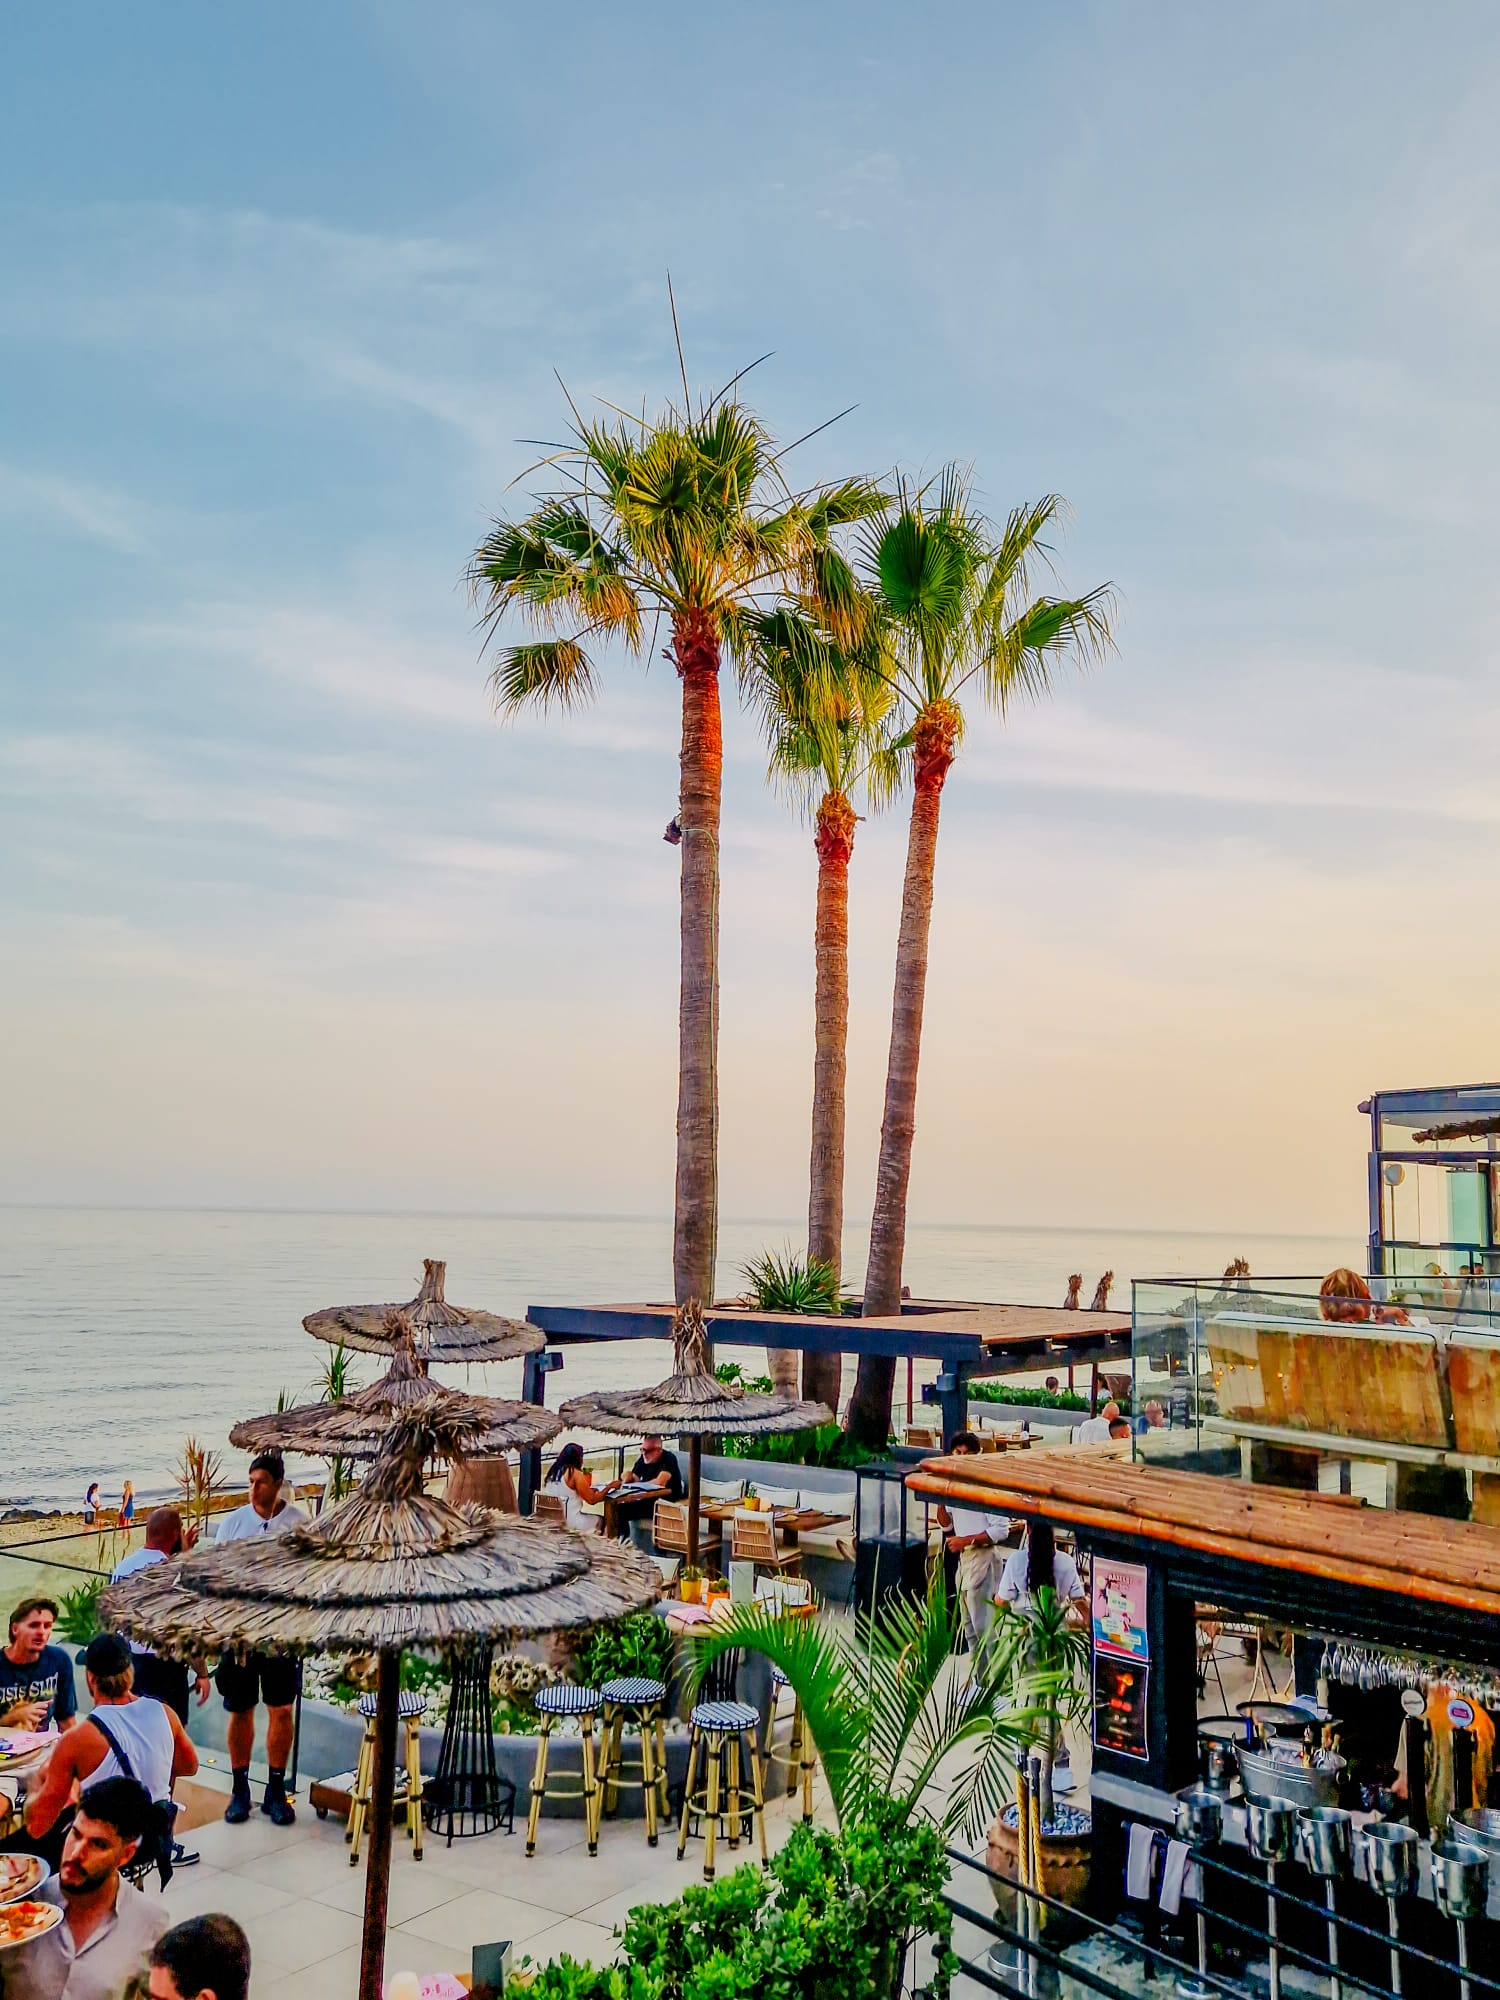
Spain’s Golden Visa program attracted a record 9,578 applications in 2023 before it officially closed in April 2025. Despite the end of the program, international demand for Spanish real estate remains strong. Behind those numbers sits a quietly transforming retirement landscape on the Costa del Sol, where Marbella has evolved from a luxury enclave into a viable year-round retirement destination with price points, healthcare infrastructure, and residency pathways that finally match the lifestyle marketing.
With Spain’s Golden Visa now closed, U.S. retirees still have a clear path to live in Spain through the Non-Lucrative Visa, provided they can show sufficient passive income, private health insurance, and meet the standard residency requirements.
After living in Marbella for seven years and working with dozens of North American retirees navigating property purchases here, I’ve watched this market mature beyond the glossy brochures. The Costa del Sol retirement story isn’t what most buyers expect when they arrive—it’s simultaneously more accessible and more nuanced than the “European dream” pitch suggests.
Current Pricing Reality: What €300,000 Actually Buys You
The Marbella property market operates in distinct pricing tiers that don’t always align with what retirees from the USA and Canada expect from “Spanish coastal real estate.”
In the €250,000–€350,000 range—the sweet spot for most retirement buyers—you’re looking at 2-bedroom apartments in established complexes 2–4 kilometers from the coast. These aren’t the beachfront properties featured in marketing materials, but they’re what 68% of North American retirees actually purchase according to 2023 transaction data from the Marbella Association of Estate Agents.
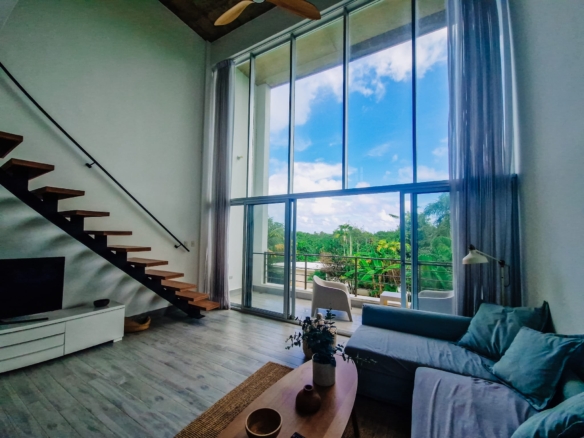
Typical apartment characteristics in this bracket: 85–110 square meters, community pool, parking space, often an elevator. Locations like Nueva Andalucía, San Pedro de Alcántara, or the eastern districts near Elviria. Monthly community fees run €120–€200, which always surprises buyers who’ve never dealt with Spanish comunidad costs.
The €400,000–€600,000 range opens access to either larger apartments (3 bedrooms, 130+ square meters) in the same areas, or smaller properties within walking distance to beaches in Marbella’s Golden Mile or Nueva Andalucía’s golf valley. This tier also includes ground-floor units with private gardens—highly sought after by retirees who want outdoor space without villa maintenance burdens.
Above €750,000, you enter villa territory. Detached homes with pools, typically 200+ square meters on 400–800 square meter plots. Be realistic about maintenance here: villa upkeep costs €400–€700 monthly once you factor in pool service, garden maintenance, and the reality that Spanish construction standards from the 1990s and early 2000s require consistent attention.
Rental Yield Analysis: The Numbers Tourism Brochures Don’t Mention
If you’re considering rental income as part of your retirement strategy, the Costa del Sol delivers yields that range from disappointing to solid depending entirely on property type and your tolerance for active management.
Long-term rental yields (12-month leases) average 4.2%–5.1% gross in Marbella’s mid-market segments. A €300,000 apartment might generate €1,200–€1,400 monthly in long-term rent. After community fees, IBI property tax (€600–€900 annually), and income tax (19%–24% for non-residents on rental income), net yields drop to 3.1%–3.8%.
Short-term vacation rentals push gross yields to 6.5%–8.2% in well-located properties, but this comes with three critical caveats retirees often underestimate:
First, Marbella’s short-term rental regulations now require a VFT license (Vivienda con Fines Turísticos), which many apartment communities prohibit in their internal rules. Verify this before purchasing if rental income factors into your retirement math.
Second, vacation rental management isn’t passive. Either you’re hands-on with guest communication, cleaning coordination, and maintenance issues, or you’re paying a management company 20%–28% of gross revenue. The retirement lifestyle you imagined doesn’t usually include 2 AM calls about broken air conditioning from German tourists.
Third, vacancy rates matter. Marbella’s high season runs April through October. November through March sees 40%–55% vacancy rates for vacation rentals. Annual occupancy averaging 65%–72% is realistic for well-managed properties—factor that into yield calculations.
Growth Outlook: Infrastructure Investment Driving Long-Term Value
Marbella’s property market appreciated 7.8% in 2023 according to Tinsa valuation data, outpacing Spain’s national average of 4.1%. But this wasn’t speculative bubble growth—it’s anchored in tangible infrastructure improvements that directly impact retirement quality of life.
The Costa del Sol Hospital expansion completed in 2022 added 127 beds and specialized cardiology and oncology departments. For retirees evaluating healthcare access, this matters more than beach proximity. The hospital now handles procedures that previously required transfers to Málaga, cutting emergency response times and expanding specialist availability.
Málaga Airport’s Terminal 3 expansion, operational since late 2023, increased capacity to 25 million passengers annually. Direct flights from Toronto, New York, and seasonal routes from Calgary and Montreal make family visits feasible without the connection complexity that plagued earlier years.
The highway AP-7 toll elimination in 2020 continues reshaping how retirees experience the coast. The 30-minute drive to Málaga’s cultural offerings or eastward to quieter coastal towns became economically friction-free, effectively expanding Marbella’s livability radius.
These aren’t cosmetic upgrades—they’re structural improvements that support property values through enhanced functionality rather than speculation. Markets built on infrastructure tend to appreciate steadily rather than dramatically, which suits retirees prioritizing stability over aggressive returns.
Comparative Analysis: Costa del Sol vs Caribbean and Latin American Alternatives
Position the Costa del Sol against popular Caribbean and Latin American retirement destinations, and distinct trade-offs emerge.
Property costs sit 35%–45% higher than comparable quality in Cabarete or other Dominican Republic coastal markets. A €350,000 Marbella apartment equals roughly $425,000 USD at current exchange rates—that same budget secures beachfront or near-beachfront property in the DR with lower community fees and property taxes.
But healthcare infrastructure heavily favors Spain. The Costa del Sol’s public and private hospital network, combined with reciprocal EU healthcare access, provides medical security that Caribbean markets can’t match. For retirees in their 60s and 70s, this isn’t abstract—it’s the difference between aging in place confidently versus contingency planning for medical evacuation.
Tax treatment varies significantly by your financial situation. Spain taxes worldwide income for residents, while the Dominican Republic offers more favorable territorial taxation. A retiree with significant pension and investment income needs proper tax planning before committing to Spanish residency—the savings from lower property prices elsewhere might disappear in higher income tax liability.
Climate tells an interesting story. Marbella delivers 320 days of sunshine annually with genuinely temperate winters—daytime highs of 16–18°C (61–64°F) in January and February. The Caribbean offers warmer winters but also hurricane season risk and the relentless heat-humidity combination from June through September that wears on many retirees over time.
The Investment Thesis for Retirement Property in Marbella
Buy Marbella real estate for retirement if your priorities align with European lifestyle, healthcare security, and geographic access to both Spain and the broader EU. The investment case strengthens when you value stability over aggressive appreciation, cultural infrastructure over beach proximity, and established legal frameworks over frontier market opportunity.
Avoid Marbella if your retirement budget stretches thin above €300,000 total property investment, if rental income represents a critical component of your retirement cash flow, or if you’re seeking the lowest possible cost of living rather than European lifestyle with cost trade-offs.
The properties that make sense for retirement aren’t the luxury villas marketed in glossy campaigns. They’re the well-located 2- and 3-bedroom apartments in established communities with solid infrastructure, reasonable community fees, and proximity to healthcare rather than golf courses.
Your move timing matters less than your residency planning. Secure legal and tax advice before purchasing, not after. The Golden Visa provides a residency pathway, but the tax implications of Spanish residency activation require professional navigation to avoid expensive surprises.
Ready to explore hand-selected properties that match the retirement reality rather than the marketing fantasy? Browse our curated Marbella listings featuring properties we’d recommend to our own parents retiring to the Costa del Sol.


Join The Discussion